

 Facebook
 X
 Pinterest
 Copy Link
A buyer finds an Irvine home they like. The location works, the property meets their needs, and they can picture themselves living there.
Then the lender updates the payment.
Mortgage rates have moved higher, and the monthly cost is hundreds of dollars more than the buyer expected. The excitement disappears and is replaced by a much harder question:
Is now really a good time to buy a home in Irvine?
The honest answer is that it may be, but not for everyone.
For some buyers, today’s higher rates make the payment unreasonable, and waiting is the right decision. For others, the payment remains manageable and the slowdown created by those same rates may provide a better negotiating opportunity.
The answer depends on your finances, your reasons for moving, how long you expect to own the home, and the specific Irvine property you are considering.
It should never depend on someone convincing you that it is always a good time to buy real estate.
Mortgage Rates Have Changed the Irvine Housing Market
There is no point pretending rates are favorable.
According to Mortgage News Daily, its top-tier 30-year fixed mortgage-rate index reached 7.60% on September 30, 2026. That was the highest level in nearly three years.
The effect on affordability is substantial, particularly at Irvine home prices.
Higher rates increase the payment associated with the same loan amount. Buyers must either accept a higher payment, increase their down payment, reduce their target price, or postpone the purchase.
Rates have also been volatile. That makes it tempting to build a purchase plan around the hope of refinancing after rates decline.
That is not a sound starting point.
A future refinance may become available, but no one can promise when rates will fall, how far they will fall, or whether a particular homeowner will qualify when the time comes. The purchase should make financial sense using the payment available now.
If refinancing later improves the situation, that should be treated as a potential benefit, not something required to make the original purchase affordable.
Higher Rates Have Also Reduced Buyer Competition
The same rates making Irvine homes more expensive have pushed many buyers out of the market.
Irvine is part of the broader Orange County housing market, so countywide inventory, demand, and mortgage-rate trends directly affect local buyer activity.
According to the September 28, 2026 Orange County Housing Report, Orange County had:
- 4,952 active listings
- Buyer demand of 1,349 pending sales during the preceding month
- An Expected Market Time of 110 days
- Approximately 99 days of Expected Market Time for detached homes
- Approximately 128 days for attached homes
Buyer demand was at its lowest September level since 2007.
That does not mean Orange County, or Irvine specifically, suddenly has an excessive number of homes for sale. Current countywide inventory remains well below the approximately 6,400-home average from 2017 through 2019.
The slowdown is being driven primarily by fewer buyers, not a flood of homes coming onto the market.
That distinction matters.
High rates are the disadvantage. For qualified buyers, more negotiating room in Orange County and Irvine is the potential opportunity.
When demand slows, some buyers encounter fewer competing offers, more price reductions, longer market times, and sellers who are increasingly willing to discuss credits, repairs, timing, or other terms.
That does not happen with every Irvine property. A well-priced home can still sell quickly. But buyers are no longer facing the same market in which nearly every desirable listing immediately generates a bidding war.
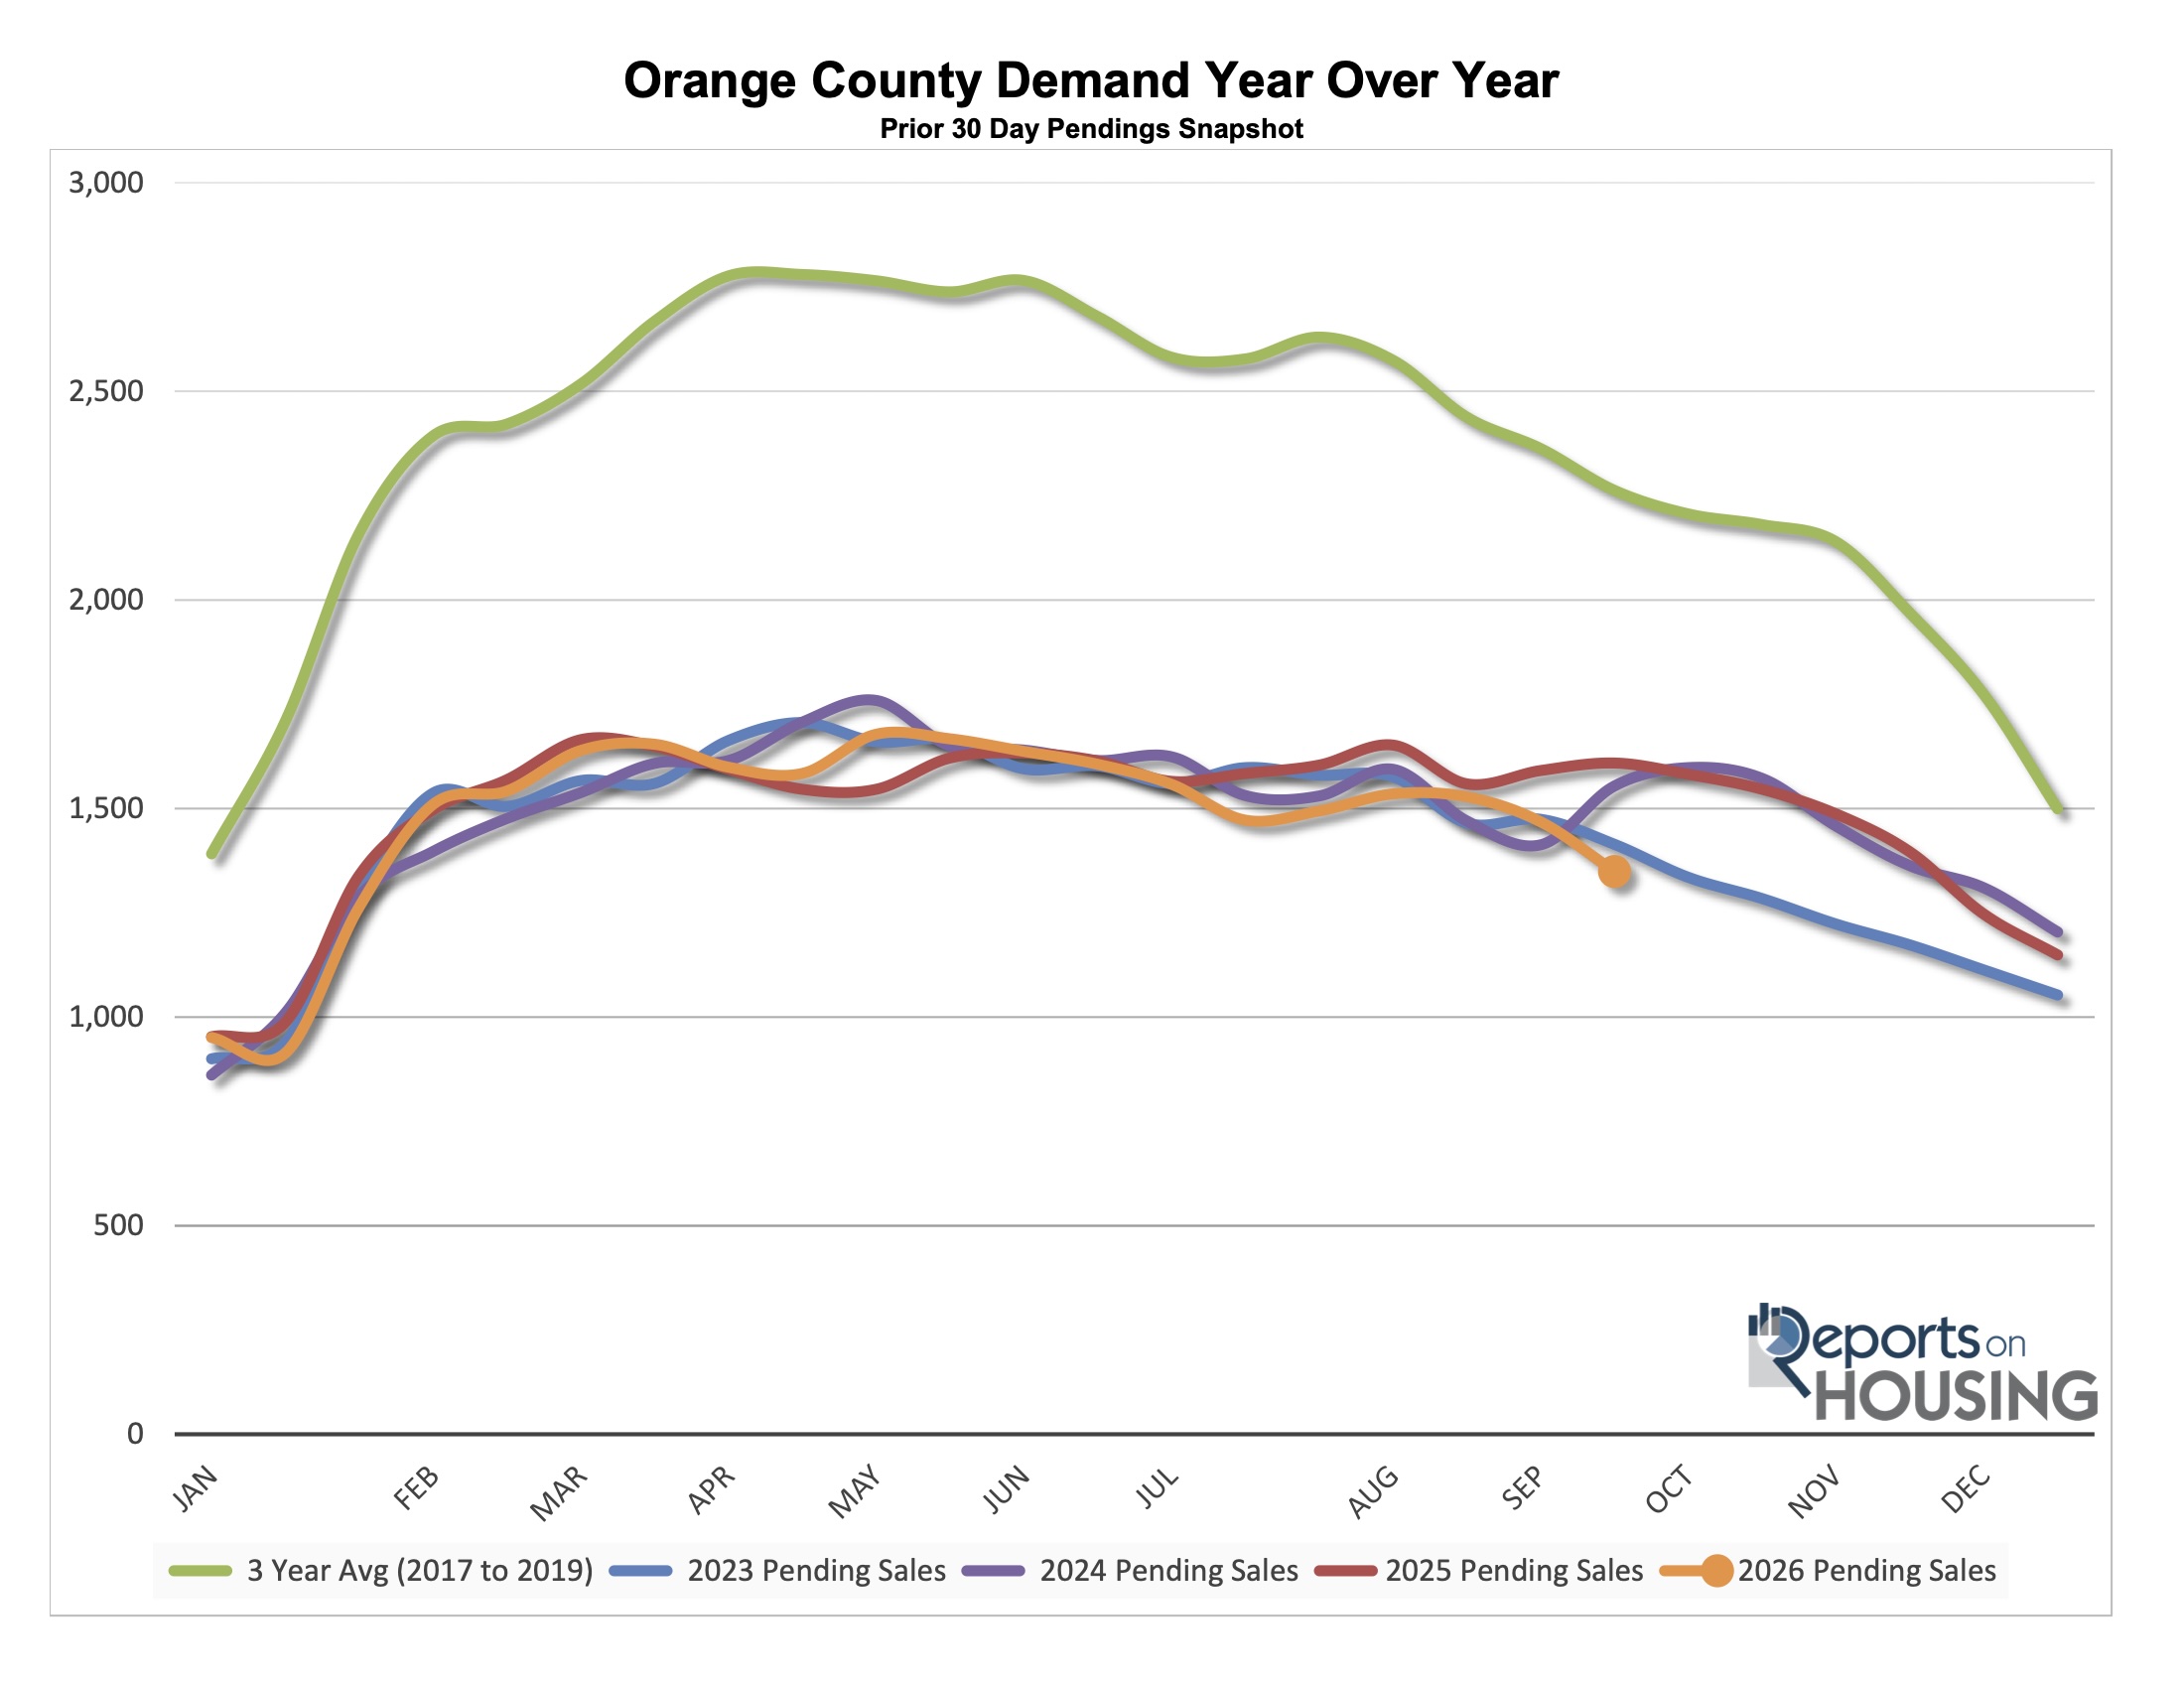
Orange County buyer demand remains well below pre-pandemic levels. Demand measures homes placed into escrow during the preceding 30 days. Source: Steven Thomas, Reports on Housing, September 28, 2026.
A Slower Irvine Market Does Not Automatically Mean a Cheap Market
This is where buyers need to separate opportunity from affordability.
An Irvine home can be more negotiable and still be unaffordable.
Suppose a seller accepts less than the original asking price or provides a credit toward closing costs. That improves the transaction, but it does not erase the effect of a mortgage rate above 7.5%.
The complete monthly cost may include:
- Principal and interest
- Property taxes
- Homeowner’s insurance
- One or more HOA assessments
- Mello-Roos or other special assessments
- Mortgage insurance, when applicable
- A reasonable allowance for maintenance and repairs
These additional costs can vary significantly between Irvine properties.
An older home may have no Mello-Roos but require more maintenance. A newer home may have newer systems but carry higher special taxes and multiple HOA assessments. Two similarly priced homes can have materially different monthly ownership costs.
The question is not simply whether you can qualify for the payment.
The better question is whether you can comfortably make it while continuing to save, maintain adequate reserves, and handle the other expenses in your life.
A lender determines what you may qualify to borrow. You still need to decide what you are comfortable paying.
When Buying an Irvine Home Now May Make Sense
Buying in the current Irvine market may make sense when:
- Your income is stable and reasonably predictable.
- You have sufficient funds for the down payment, closing costs, and reserves.
- The complete monthly payment works at today’s interest rate.
- You expect to own the home long enough to justify the transaction costs and short-term market risk.
- The property meets a genuine housing need rather than creating unnecessary financial strain.
- You are willing to evaluate the individual property rather than relying on market headlines.
- You can negotiate protections and terms without abandoning appropriate inspections and contingencies.
These buyers may benefit from the reduced competition.
An Irvine home that has been on the market for several weeks, experienced a price reduction, fallen out of escrow, or received limited buyer activity may present an opportunity to negotiate. These are often the same characteristics to look for when trying to find a better deal on an Orange County home.
That negotiation could involve price, closing-cost credits, repairs, appliances, occupancy, or timing.
The opportunity is not necessarily finding an Irvine home at a dramatically discounted price. It may be having enough breathing room to investigate the property carefully and negotiate a more balanced transaction.
When Waiting May Be the Better Decision
There is nothing wrong with deciding not to buy.
Waiting may be the better choice when:
- The payment only works if mortgage rates decline soon.
- Purchasing would leave you without sufficient emergency reserves.
- Your income or employment is uncertain.
- You expect to move again within a relatively short period.
- You would need to waive important protections to complete the purchase.
- You own another home but have not established its likely value and net proceeds.
- The purchase depends on several optimistic assumptions happening exactly as planned.
- You are buying primarily because someone told you Irvine prices or mortgage rates are guaranteed to rise.
Buying a home does not become a good decision merely because a seller is willing to negotiate.
If the payment creates significant financial strain, walking away may be the smartest decision you make.
Should Irvine Buyers Wait for Lower Mortgage Rates?
Possibly, but waiting is not automatically free.
Lower rates would improve affordability if prices and other conditions remained unchanged. The problem is that housing markets do not hold everything else constant while one variable moves.
If mortgage rates decline meaningfully, some buyers who left the Irvine market may return. Increased demand can create more competition, reduce seller flexibility, and put upward pressure on prices. In plain terms, lower mortgage rates could mean higher home prices.
That does not mean you should rush to buy before rates fall. It means the decision is not as simple as:
“I will wait for a lower rate and buy the same Irvine home later.”
The home may no longer be available. The seller may be less negotiable. Other buyers may be competing for it. Prices may be higher, lower, or essentially unchanged.
No one knows the exact combination that will exist several months from now.
Run the purchase using today’s payment. Then compare it with reasonable alternative scenarios. If buying only makes sense under the most optimistic forecast, it probably does not make sense yet.
Is Irvine Headed for Another 2008?
Slow demand and high rates naturally bring back memories of the Great Recession.
I worked through that market, including the short sales and underwater mortgages that came with it. The current Irvine and Orange County markets have serious affordability problems, but they do not have the same underlying structure.
The September 28 Orange County Housing Report identified only 13 active foreclosures and short sales combined. That is closer to a rounding error than a sign of another 2008-style housing crisis. Through August 2026, Orange County recorded 25 distressed closings, compared with 10,244 during all of 2008.
Today’s homeowners generally have more equity, and the lending practices that produced widespread unsustainable loans before the Great Recession are not dominating the current market.
That does not guarantee Irvine home values will rise. Prices can flatten or decline when demand remains weak. Individual homeowners can also experience financial distress.
But a slower market is not automatically a foreclosure crisis.
Waiting for a repeat of 2008 is not a purchasing strategy. It is a prediction, and the current Orange County data does not support it.
Irvine Is Not One Market
Countywide figures help explain the overall direction, but they do not tell you whether a particular Irvine home is a good purchase.
Even within Irvine, two similarly priced homes may have very different:
- Days on market
- Price-reduction histories
- Competing listings
- HOA costs
- Mello-Roos and other assessments
- Property conditions
- Insurance considerations
- Seller circumstances
- Recent comparable sales
A townhome with multiple HOA assessments and deferred updating may face different buyer resistance than a detached home with a similar price. A newer home with substantial Mello-Roos may produce a higher monthly cost than an older home with a similar purchase price.
A listing that has been sitting for 60 days may provide more negotiating room than a new listing that attracted immediate interest. But days on market alone do not tell the whole story. If that same home just reduced its price by $100,000, it may now be priced closer to market value and suddenly attract strong interest or competing offers. Review how long the home has been available at its current price and how buyers have responded since the adjustment.
Even two Irvine homes with the same floor plan can perform differently because of condition, upgrades, location within the tract, parking, lot characteristics, view, or proximity to a busy street.
The village name, countywide average, or national headline does not determine your leverage.
The individual listing does.
Before writing an offer, review the property’s listing history, comparable sales, current competition, condition, complete ownership costs, disclosures, and apparent market response.
That is how you determine whether the slower market has created a real opportunity or merely made an overpriced property sit longer.
How to Approach the Irvine Market Right Now
If you are considering buying an Irvine home, start with these steps:
- Establish a comfortable payment. Ask a licensed lender to calculate the complete monthly obligation at current rates.
- Test a higher-rate scenario. Rates can move before they are locked. Know what a further increase would do to your payment.
- Protect your reserves. Do not use every available dollar simply to complete the purchase.
- Compare the individual property with its competition. Review recent sales, active listings, price reductions, days on market, and prior escrow history.
- Calculate the complete ownership cost. Include HOA dues, Mello-Roos, other special assessments, insurance, taxes, and expected maintenance.
- Negotiate the whole transaction. Price matters, but so do credits, repairs, contingencies, occupancy, and timing.
- Do not depend on a future refinance. The payment should work before any possible rate reduction.
- Be willing to walk away. A slower market is only useful if you maintain discipline.
Buyers who already own a home should also determine their likely sale proceeds before establishing the next-home budget. I explain that process in Before You Buy Your Next Orange County Home, Know These Two Numbers.
So, Is Now a Good Time to Buy a Home in Irvine?
For some buyers, yes.
If your finances are stable, the current payment is comfortable, the home meets your longer-term needs, and the individual listing provides a reasonable opportunity, today’s reduced competition may work in your favor.
For other buyers, no.
If the payment requires financial strain, depends on a quick refinance, depletes your reserves, or only works under optimistic assumptions, waiting is the better decision.
Redfin Chief Economist Daryl Fairweather recently summarized it well:
“Now is a good time to buy a home, if you can afford it.”
Her full comments are available in Redfin’s September 29 market discussion.
The most important part of that statement is not “now.” It is “if you can afford it.”
Rates are unfavorable. Buyer demand is weak. Orange County inventory remains limited compared with pre-pandemic norms. Some Irvine sellers are becoming more flexible, while properly priced homes can still attract serious buyers.
That combination does not produce one answer for everyone.
If you are considering buying a home in Irvine, I can help you evaluate the specific homes in your price range, compare their complete ownership costs, and identify where genuine negotiating room may exist.
The answer may be that buying now makes sense. It may also be that you should wait.
Either way, the decision should be based on your numbers and the individual Irvine property, not pressure, predictions, or headlines.
Mortgage-rate information is based on Mortgage News Daily as of September 30, 2026. Orange County market information is based on the September 28, 2026 Steven Thomas Orange County Housing Report. Mortgage rates and market conditions can change. This article provides general real estate information and is not lending, legal, tax, or financial advice. Buyers should obtain property-specific information and consult the appropriate licensed professionals.


